Property in two countries
This is an illustrative example, not a customer story. The numbers are made up.
Agnieszka Wróbel and Mikkel Sørensen live in Copenhagen with their two children, in a flat they own with a Danish mortgage. Agnieszka also owns a small flat in Kraków that she bought before they met, which is let out and has a Polish mortgage. Thallo doesn't split ownership between people, so they track the household as one, with full balances, and their display currency is DKK.
This example is mostly about the two flats: how they're valued, and how much of the household's net worth they make up.
Their accounts
| Account | Type | Currency | Balance on 31 March |
|---|---|---|---|
| Joint current account | Cash | DKK | DKK 60,000 |
| Mikkel's pension | Retirement | DKK | DKK 400,000 |
| Copenhagen flat | Property | DKK | ≈ DKK 3,200,000 |
| Copenhagen mortgage | Mortgage | DKK | DKK 2,100,000 |
| Polish bank account (rent comes in here) | Cash | PLN | PLN 20,000 |
| Kraków flat | Property | PLN | ≈ PLN 600,000 |
| Kraków mortgage | Mortgage | PLN | PLN 250,000 |
The mortgages are entered as positive numbers and Thallo subtracts them.
On 31 March, 1 PLN was worth DKK 1.75 and their net worth was DKK 2,207,500.
Valuing the two flats
Nobody sends a statement for a flat, so both values are their own estimates. They're marked ≈ and set to a yearly rhythm.
They had last valued the Copenhagen flat in April the year before, so by June its value was 14 months old and the flat was marked out of date. Agnieszka looked at recent sales on their street and confirmed DKK 3,200,000. Confirming a value counts as an update, so the flag was cleared.
In June, a flat two floors below hers in Kraków was sold. She looked at the sale price and a few listings on the same street, and raised her estimate from PLN 600,000 to PLN 660,000. The old figure had also been an estimate, and an older one, so she replaced it.
The rest of the quarter
- The joint account went from DKK 60,000 to DKK 75,000.
- Mikkel's pension went from DKK 400,000 to DKK 410,000.
- The Copenhagen mortgage came down to DKK 2,085,000.
- Rent took the Polish account from PLN 20,000 to PLN 26,000, and the Kraków mortgage came down to PLN 244,000.
By 30 June the zloty had fallen to DKK 1.70. Their net worth on 30 June was DKK 2,351,400, up DKK 143,900 for the quarter.
How much of it is property
In the breakdown by category, most of their net worth is in Illiquid, estimated, which here means the two flats. Their only liquid accounts are the two current accounts, which came to about DKK 119,200 on 30 June (DKK 75,000 plus PLN 26,000 at 1.70). The new Kraków estimate didn't change that figure.
Where the quarter's rise came from
Account by account, 31 March to 30 June looks like this:
| Account | Currency effect | Balance changes |
|---|---|---|
| Joint current account | DKK 0 | +DKK 15,000 |
| Mikkel's pension | DKK 0 | +DKK 10,000 |
| Copenhagen flat | DKK 0 | DKK 0 |
| Copenhagen mortgage | DKK 0 | +DKK 15,000 |
| Polish bank account | −DKK 1,000 | +DKK 10,200 |
| Kraków flat | −DKK 30,000 | +DKK 102,000 |
| Kraków mortgage | +DKK 12,500 | +DKK 10,200 |
| Total | −DKK 18,500 | +DKK 162,400 |
What moved shows the three Polish lines as one PLN row of −DKK 18,500, and leaves out the Copenhagen flat, which didn't change.
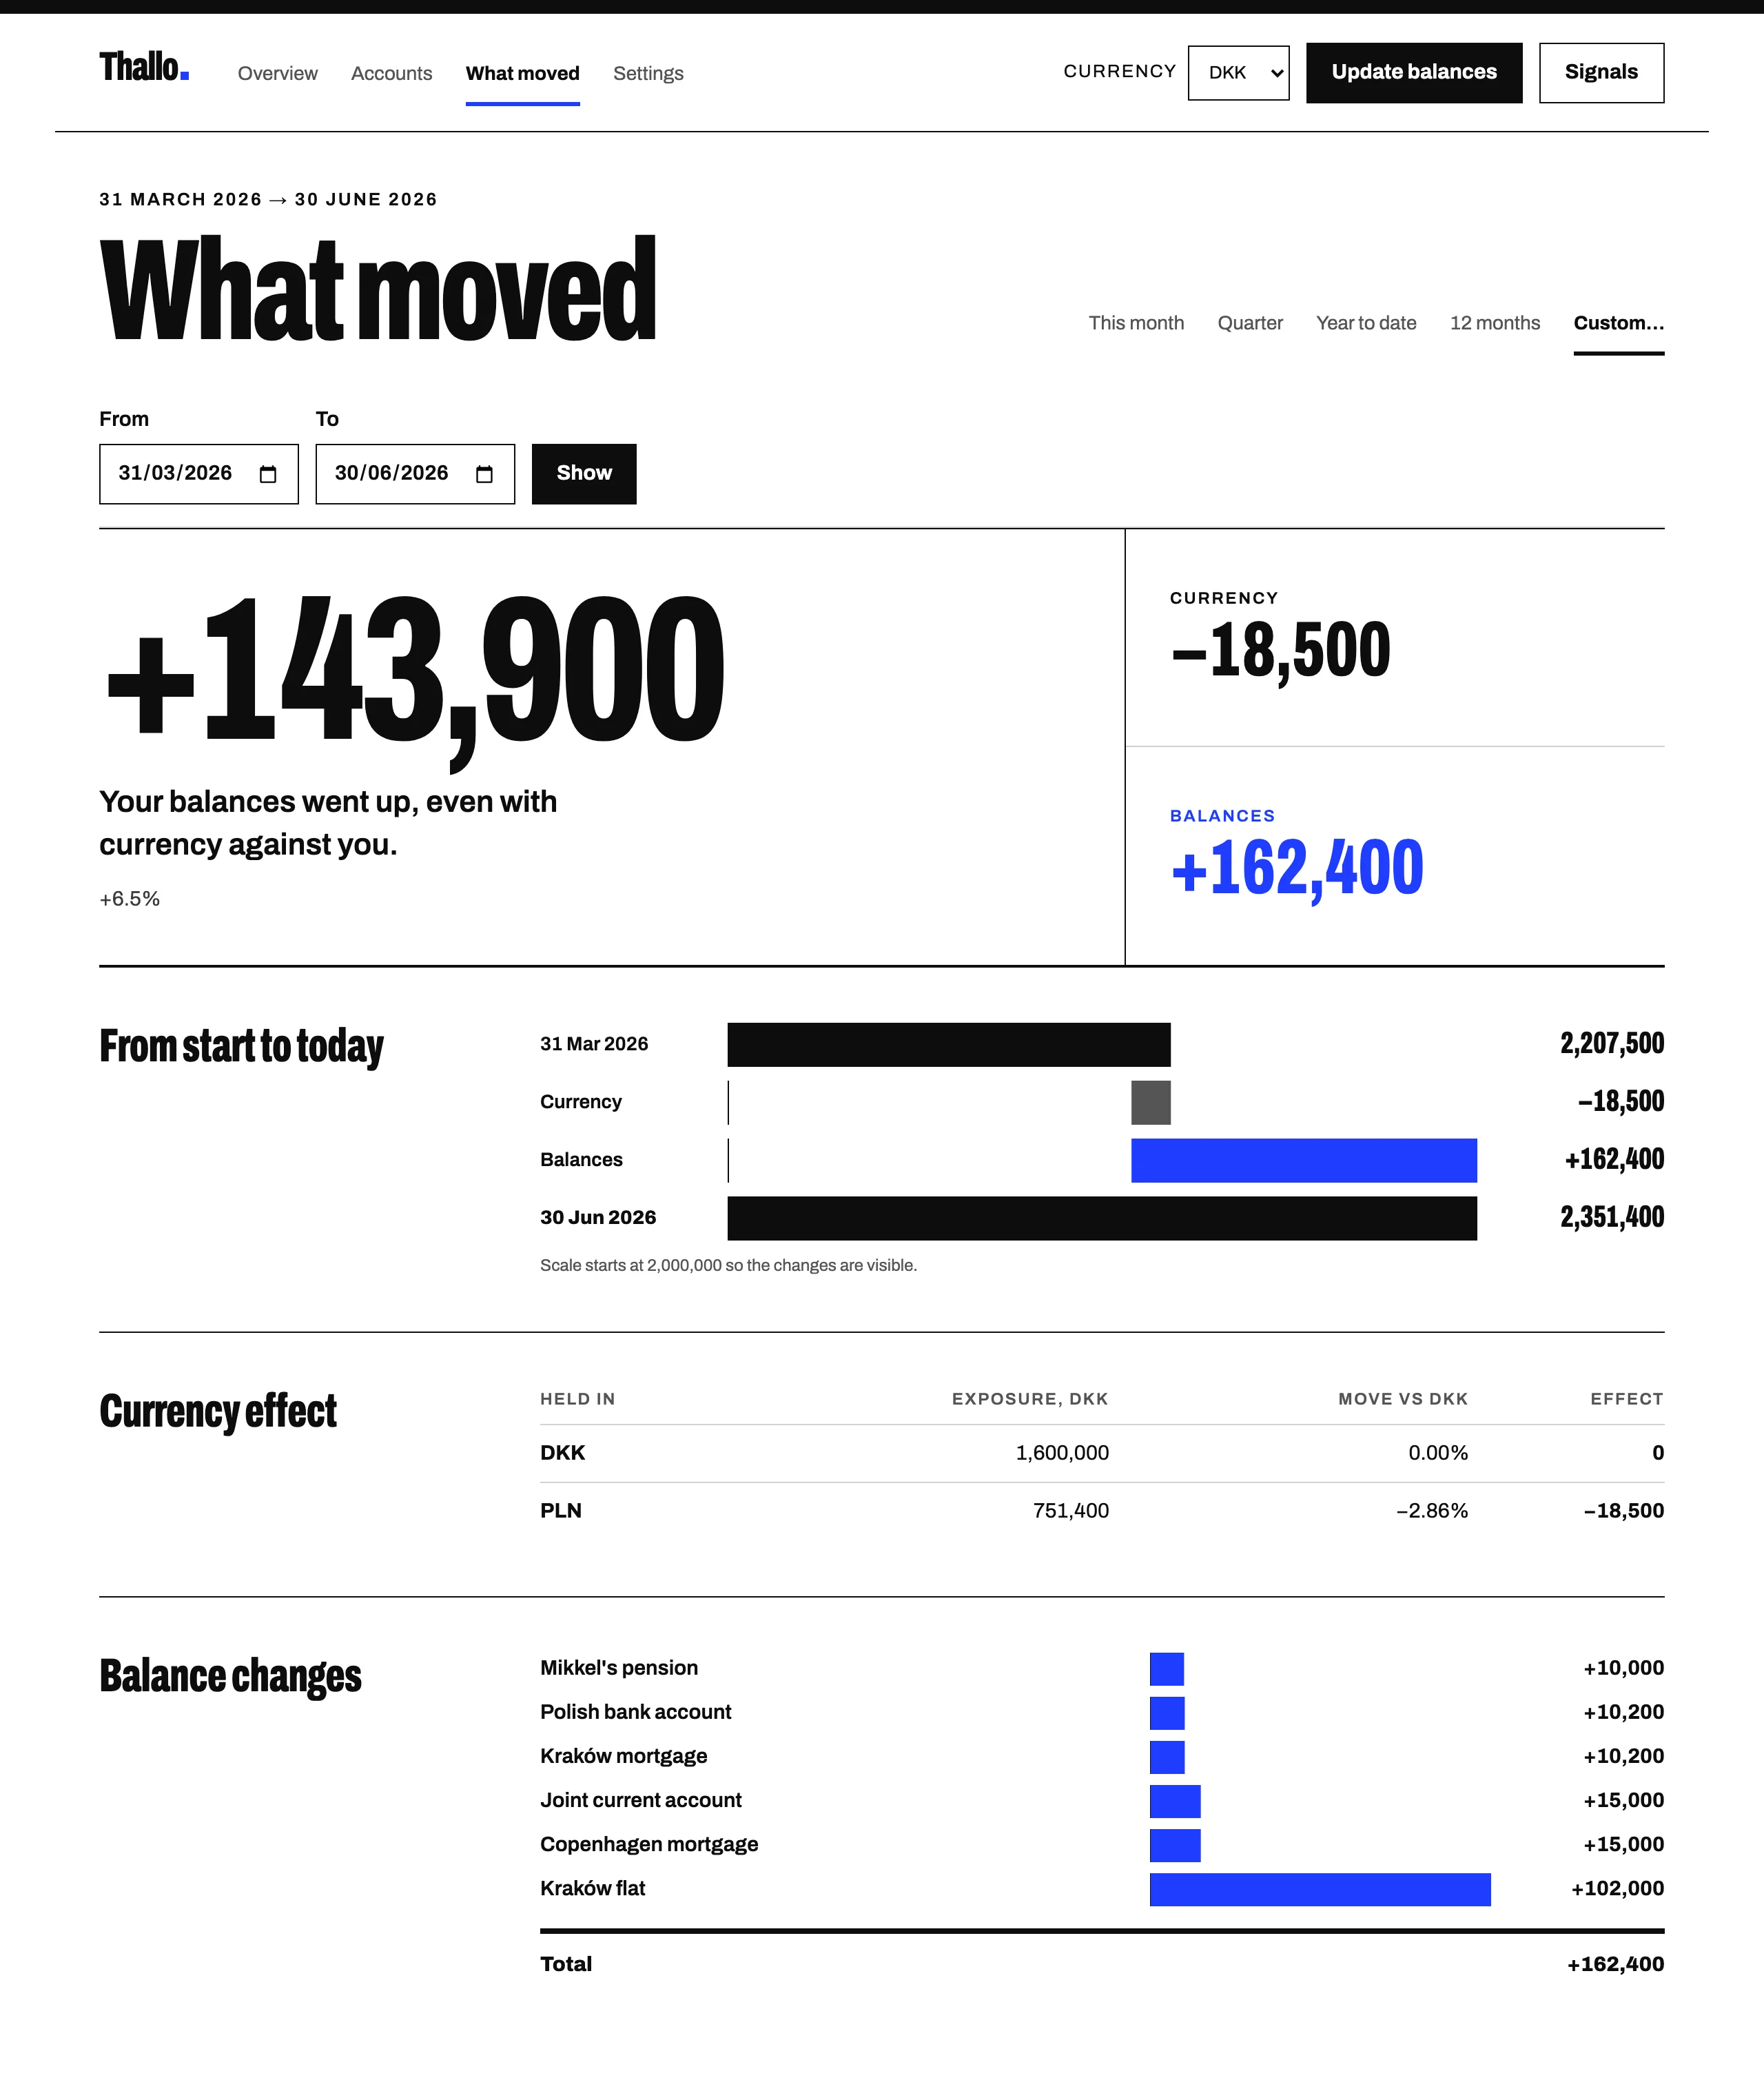
A smaller mortgage shows as a positive change, because they owe less.
DKK 102,000 of the rise came from the new Kraków estimate. It's based on a real sale nearby, so it's a reasonable figure, but it's still their estimate and not money they've received.
The weaker zloty took DKK 30,000 off the value of the Kraków flat in kroner. The mortgage made up some of that, because a debt in zloty also gets smaller in kroner when the zloty falls: PLN 250,000 × 0.05 = DKK 12,500. Their Signals that week included: "The zloty fell against the krone this quarter. Your Polish accounts lost about DKK 18,500 in kroner, net of the mortgage."
Without the two flats, balance changes for the quarter came to DKK 60,400. That covers the two current accounts, the two mortgage payments and the pension, whose DKK 10,000 includes any investment growth. It leaves out both their own estimates and the exchange rate.
Start free with the accounts in one country, and add the other country's when you have the numbers.